 A Note From Diana
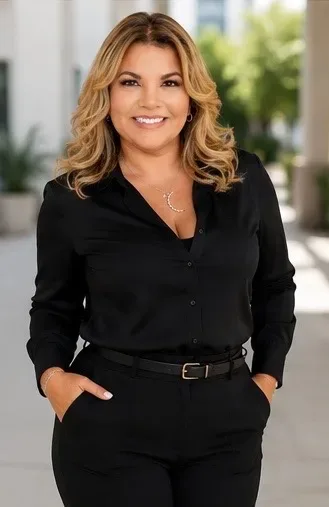
As a licensed Realtor with Fig Team EXP Realty LLC, I've guided dozens of buyers through the contract-to-close process in Southwest Florida. I'm a bilingual specialist, the wife of a retired Green Beret, and someone who takes the journey from offer to closing day personally.
"Going under contract is one of the most exciting moments in the home buying journey — but it can also feel overwhelming if you don't know what's coming. Here's your roadmap."
— Diana Austin, Realtor | Fig Team EXP Realty LLC
Your Offer Is Accepted — Now What?
Timeline: Day 1
Congratulations — the seller accepted your offer. Here's what happens immediately:
- Your earnest money deposit is due (typically 1–3% of the purchase price). This is deposited into an escrow account held by the title company or closing attorney.
- Your agent sends the fully executed contract to the title company, lender, and all parties.
- The clock starts ticking — every deadline in your contract has a specific date attached to it.
- You'll receive a copy of your signed contract — keep it in a safe place.
What Diana Does for You
- Coordinates with the seller's agent, title company, and lender
- Sends you a timeline of every deadline so you know exactly what's due and when
- Begins scheduling your inspections
Important: Your earnest money is NOT extra money — it's applied toward your purchase at closing. If you back out without a valid reason under the contract, you could lose it.
Home Inspection
Timeline: Days 1–10 (typically within 7–10 days of contract)
This is one of the most important steps. A licensed home inspector examines the property from top to bottom.
What Gets Inspected:
What You Should Do:
- Attend the inspection if possible — your inspector will walk you through findings
- Ask questions about anything you don't understand
- Don't panic — no house is perfect. The goal is to identify major issues
Cost: $300–$500 for a standard home inspection
Florida-Specific Inspections to Consider
Wind Mitigation Inspection
Checks hurricane-resistant features — can save you money on insurance
$75–$150
4-Point Inspection
Covers roof, electrical, plumbing, HVAC — often required by insurers for homes over 20 years
$75–$150
Termite / WDI Inspection
Checks for termites and other wood-destroying organisms
$50–$100
Sewer Scope
Camera inspection of the sewer line
$100–$300
Mold Inspection
If there are signs of moisture
$300–$600
Pool Inspection
If the property has a pool
$100–$200
Reviewing the Inspection Report
Timeline: Days 7–12
After the inspection, you'll receive a detailed report (usually 30–60+ pages). Here's how to handle it:
Review the Report Carefully:
- Focus on major systems: roof, HVAC, plumbing, electrical, foundation
- Note any safety issues (mold, structural problems, electrical hazards)
- Don't stress about cosmetic issues — those are normal
Decide on Your Options:
Accept the property as-is
If the inspection found no major issues
Request repairs
Ask the seller to fix specific items before closing
Request a price reduction
Ask for a credit so you can handle repairs yourself after closing
Walk away
If the issues are too significant and you have an inspection contingency
Diana Will Help You
- Interpret the inspection findings
- Negotiate repairs or credits with the seller's agent
- Get contractor estimates if needed
- Advise you on what's worth fighting for and what's not
Pro Tip: In a competitive market, requesting minor repairs can sometimes weaken your position. Focus on major issues — safety, structural, and expensive systems. Leave the cosmetic stuff alone.
Home Appraisal
Timeline: Days 10–20
Your lender orders an appraisal to confirm the property's market value supports the loan amount.
What Happens:
- A licensed appraiser visits the property and measures the home, takes photos, and notes the condition and features
- They compare the property to recent sales of similar homes in the area
- They provide a written opinion of value to the lender
Cost: $300–$600 (paid by you, the buyer)
If the Appraisal Is Low:
Diana will help you navigate any appraisal issues — this is where having an experienced agent matters.
Mortgage Processing and Underwriting
Timeline: Days 1–30 (runs concurrently with inspections and appraisal)
While inspections and appraisal are happening, your lender is working on your loan.
What's Happening Behind the Scenes:
- Document verification: income, assets, debts, employment
- Credit review: your credit is monitored throughout the process
- Title search: the title company verifies the property has a clear title (no liens, disputes, or legal issues)
- Insurance: you'll need to secure homeowner's insurance before closing
- Underwriting: the lender's underwriter reviews everything and makes the final lending decision
What You Need to Do
- RESPOND QUICKLY to lender requests for documents
- Don't make any large purchases or open new credit accounts
- Don't change jobs if possible (this can complicate the process)
- Keep your financial situation stable — no big deposits or withdrawals without explanation
- Stay in close communication with your loan officer
Common Lender Requests:
Secure Homeowner's Insurance
Timeline: Days 15–25
You MUST have homeowner's insurance before closing. In Florida, this is especially important and can take time.
What You Need:
- Homeowner's insurance (covers the structure, personal property, and liability)
- Flood insurance (required if in a flood zone — FEMA or private)
- Wind/Hurricane insurance (may be separate from your homeowner's policy in Florida)
How to Shop:
- Get quotes from multiple insurance companies
- Your lender will require specific coverage amounts
- Diana can recommend insurance agents who work with Florida properties
- Budget $2,500–$8,000+ per year depending on the property, location, and coverage
Florida-Specific Considerations
- Insurance rates have increased significantly in recent years
- Older homes may have higher premiums or difficulty getting coverage
- Wind mitigation and hurricane features can reduce your premium
- Flood insurance is separate from homeowner's and is required in flood zones
- Start shopping EARLY — don't wait until the last minute
Final Walkthrough
Timeline: 1–2 days before closing
This is your last chance to see the property before it becomes yours.
What to Check:
- All agreed-upon repairs have been completed
- The property is in the same condition as when you made the offer
- No new damage or issues
- All appliances and systems are functioning
- The seller has removed all their belongings (unless otherwise agreed)
- Trash and debris have been removed
What to Bring:
Pro Tip: Don't skip the final walkthrough. Things can change between inspection and closing — make sure everything is as expected.
Closing Day
Timeline: The big day!
This is when you officially become a homeowner. Here's what to expect:
Before Closing:
- Review your Closing Disclosure (CD) — your lender provides this at least 3 business days before closing. Compare it to your original Loan Estimate and ask about any differences
- Wire your closing funds — DO NOT wire money without calling the title company directly to verify wiring instructions. Wire fraud is real. Call using a verified phone number, not one from an email
- Bring your ID and any remaining documents
At the Closing Table:
- You'll sign a LOT of documents — mortgage, deed, disclosures, and more
- The closing agent (title company or attorney) will explain each document
- Bring a valid government-issued photo ID
- Closing typically takes 45 minutes to 1.5 hours
- You may be able to close remotely with a power of attorney or mobile notary
What You'll Pay at Closing:
After Signing:
- The deed is recorded with the county
- You receive the keys to your new home!
- The title company distributes funds to the seller
After Closing — The First 30 Days
You're officially a homeowner. Here's what to handle in your first month:
Week 1
- Change the locks
- Set up utilities: FPL, water, internet, trash
- Update your address (USPS, bank, subscriptions, employer)
- Locate breaker box, water shut-off, and A/C filter
Week 2
- Deep clean the house
- Begin planned renovations or repairs
- Meet your neighbors
- Register vehicle in Florida (within 10 days)
- Get a Florida driver's license (within 30 days)
Weeks 3–4
- Set up a home maintenance schedule
- Replace A/C filters (every 1–3 months in Florida)
- Schedule pest control (quarterly in Florida)
- Set up pool maintenance if applicable
- File your homestead exemption (deadline March 1)
- Store your homeowner's insurance policy safely
Common Questions Buyers Ask
How long does the whole process take?
Can I back out after going under contract?
What if the appraisal is low?
What if I lose my job during the process?
Can I do renovations before closing?
What's the difference between closing costs and down payment?
Do I need to be at closing in person?
Diana's Personal Note
Realtor, Fig Team EXP Realty LLC
Closing day is one of my favorite moments as a Realtor — seeing my clients get the keys to their new home never gets old. The process between offer and closing can feel long and overwhelming, but I'm with you every step of the way.
I'll send you deadlines, remind you of important dates, answer your calls at 10 PM when you're worried about something, and celebrate with you at the closing table.
Buying a home is a big deal. You deserve an agent who treats it that way. That's what I do.
"I have got your back."