A Personal Note from Diana
Approval Anxiety Is Normal. Being Prepared Is the Cure.
Almost every buyer I have ever worked with has asked, at some point, "What if I don't qualify?" It is a fair question, and it deserves a calm, honest answer, not a sales pitch. Here is the truth: you do not need perfect credit or a huge down payment to buy a home in Southwest Florida. You need a clear picture of your numbers, the right documents in order, and a lender who explains things instead of confusing you.
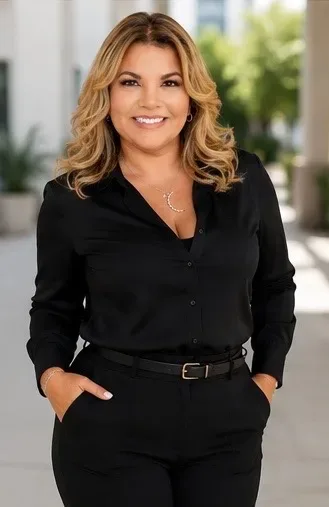
I'm Diana Austin, a bilingual Realtor with Fig Team EXP Realty LLC, serving Cape Coral, Fort Myers, Estero, Bonita Springs, and Naples. My favorite moment in this whole job is watching a nervous buyer realize, wait, I can actually do this. That is what pre-approval is for. It turns a scary question mark into a plan you can hold in your hand. Let's walk through it together, one calm step at a time.
"My goal is simple: you should feel informed and protected, not overwhelmed. Knowing your number before you start shopping is the single best thing you can do for your sanity, and your budget."
Pre-Qualified, Pre-Approved, or Underwritten: What Do the Three Stages Actually Mean?
These three words get used interchangeably, and they mean very different things. Knowing the difference keeps you from being surprised later, and it tells you how seriously a seller will take your offer.
Pre-qualification: a quick estimate
You tell the lender your income and debts, and they give you a rough idea of what you might afford. Nothing is verified, often no credit pull at all. It is a helpful starting point for your own planning, but it means almost nothing to a seller.
Pre-approval: verified and real
Your income, assets, debts, and employment are actually checked, and the lender runs a full credit review. You receive a letter stating the maximum loan amount you qualify for. This is the document a listing agent wants to see attached to your offer.
Underwritten approval: the strongest offer
Some lenders will run your file through full underwriting before you even make an offer, known as a fully underwritten approval. Only the property itself is left to verify. In a competitive market, this is the strongest paper you can bring, and it removes a lot of the fear around financing contingencies.
Which one should you get?
For nearly every buyer, the goal is a real pre-approval before you start touring homes. If your timeline allows, ask your lender about a fully underwritten approval, especially if you are buying in a popular neighborhood or planning to make offers quickly.
The Documents You Will Need (and Why They Matter)
Gathering paperwork is the part buyers dread most, so let me make it boring and easy. Most lenders want the same standard set, and you can usually upload it all online in one sitting.
Government photo ID
A driver's license or passport, plus your Social Security number, so the lender can run your credit and confirm your identity. It is the smallest document on this list and the one people forget most.
Pay stubs (last 30 days)
Your most recent pay stubs prove your current income. If you are paid twice a month, that usually means two stubs. Simple, verifiable, and usually the fastest proof of income there is.
W-2s and tax returns (past 2 years)
Lenders look at two full years of W-2s and federal tax returns to confirm your income is stable, not a lucky month. If you are self-employed, add your business returns and a recent profit-and-loss statement.
Bank statements (last 2 to 3 months)
Checking, savings, and money market statements show your down payment and closing funds actually exist and have been there for a while. Large, unexplained deposits usually need a letter explaining where they came from, so keep withdrawals and transfers easy to follow.
Statements for existing debts (last 60 days)
Lenders need current balances and payments on your car loan, student loans, credit cards, and personal loans so they can calculate your debt-to-income ratio honestly. Investment and retirement account statements help show assets too.
Employment contact info (past 2 years)
Lenders call employers to verify you work where you say you do and earn what you report. If you changed jobs recently, a simple letter or pay stub from the new role usually smooths the way.
What the Lender Actually Verifies
A pre-approval is not a guess, it is a review. Here is what the underwriter is looking at when they say yes, no, or "almost, send me one more document."
Your credit history
The full credit pull looks at payment history, outstanding balances, and any red flags like collections or late payments. Here is a relief: multiple lender pulls within a short mortgage-shopping window count as one on most scoring models, so you can compare lenders without wrecking your score.
Your debt-to-income ratio
This compares your monthly debts to your monthly gross income, and it is the number that decides what you can borrow. Lenders generally look for a ratio around 43 percent, and most will not stretch much past 50. It is also the number you can actually move: pay down a card, and your budget improves.
Income stability
Steady, verifiable income over two years is the gold standard. Self-employed buyers show this with tax returns and profit-and-loss statements, and veterans can lean on the VA loan program's generous income rules. New grads and recent job changers usually just need a short paper trail.
Your assets and down payment
You need enough cash for the down payment plus closing costs, and the money needs a clear paper trail. Gift funds from family are allowed on most loan programs, but they have to be documented properly. Never move money around "to make it look clean"; a straight paper trail always wins.
The Florida-Specific Rules That Can Change Everything
Southwest Florida has a personality all its own, and so does its mortgage process. These four Florida realities surprise more out-of-state buyers than anything else, and they can genuinely affect whether you qualify and how much house you can afford.
Windstorm coverage is required
Every Florida mortgage requires wind and hurricane coverage, not just homes near the coast. Most policies carry a percentage-based hurricane deductible, commonly 2 to 5 percent of your dwelling coverage, and coastal premiums can run $5,000 to $15,000 a year or more. Your lender must count that into your payment, so get a real insurance quote before you set your budget, not after.
Flood insurance is separate, and sometimes required
Standard homeowners insurance in Florida does not cover flood. If a home sits in a FEMA Special Flood Hazard Area, any federally backed mortgage requires a separate flood policy. Even outside those zones, flood risk in this region deserves a conversation, and Citizens wind policyholders are being phased into a flood requirement that finishes nationwide on January 1, 2027.
Property taxes and the homestead exemption
Most Florida lenders escrow property taxes, and Florida's tax rules are genuinely buyer-friendly. The homestead exemption trims your assessed value, the Save Our Homes cap limits increases to 3 percent a year, and portability lets you carry your existing benefit to a new Florida home. If you own a Florida home already, tell your lender, it can reduce the escrow and improve your numbers.
Condo buyers face extra scrutiny
Since the Surfside collapse, Florida condos three stories and up must complete milestone inspections and keep structural reserves funded under state law (SB 4-D), and lenders check it. Associations that fall behind can make a building "non-warrantable," meaning conventional financing disappears and only cash works. If you are eyeing a condo, I check these documents with you before you fall in love, and that is exactly the kind of thing I love doing for my buyers.
How Long Does Pre-Approval Take, and How Long Does It Last?
Two timing questions come up on every single call, so let me answer both plainly, because they shape how you plan your whole search.
Most approvals take 1 to 3 business days
Once your documents are in, most lenders complete a pre-approval within one to three business days, and some offer same-day turnaround when everything is clean. If a lender cannot meet your timeline, that is information, and you can move on. A good lender treats your deadline like their own.
The letter is valid for 60 to 90 days
Most pre-approval letters are valid for 60 to 90 days, though some lenders issue 30-day letters and others stretch to 120. Check the expiration date on yours, and if it expires, ask for a quick renewal; your lender can usually refresh it in a day or two.
Start before you shop
The right order is pre-approval first, house hunting second. You will know your number, your monthly payment range, and your non-negotiables before you walk into a single open house. You will also make offers with confidence instead of hesitation, which matters in every market, including this fall's.
Use a local lender who knows SWFL
This is the underrated hack of the whole process. A lender who works in Cape Coral and Naples every day already knows flood zones, wind insurance costs, and condo reserve rules. They will quote you a realistic payment the first time, and their appraisal and closing teams move at local speed. I can recommend lenders I trust on my preferred vendors page.
The Mistakes I See Buyers Make (and How to Avoid Them)
Most pre-approval surprises are not about credit or income, they are about things buyers do between approval and closing. Do not let a two-week decision undo six months of planning.
Making big purchases on credit
That furniture "for the new house" bought on a store card before closing can shift your debt-to-income ratio just enough to matter. The rule of thumb is simple: no major credit purchases, no new car leases, no big balance transfers between pre-approval and closing. New furniture waits for the moving truck.
Quitting or switching jobs
Lenders re-verify employment shortly before closing, sometimes within ten days. A job change or a resignation, even a great career move, can delay or undo your loan unless your lender approves it first. Talk to your lender before you change anything about your employment or finances.
Co-signing for someone else
Helping a relative co-sign a car loan mid-search is generous and can quietly wreck your debt-to-income ratio. If you plan to buy this year, keep your name off new debt, full stop, and be honest with the person you are helping about why.
Moving money without a trail
A relative offers help with the down payment, wonderful, but the deposit needs to be documented and traced. Large unexplained deposits are the classic reason loans stall in underwriting. Tell your lender about gift funds up front and follow their documentation instructions exactly.
Letting your letter expire
A pre-approval is a snapshot in time. If you have been searching for a few months, ask your lender to refresh your letter before you make your next offer so the numbers you present are current and valid.
Shopping alone and guessing
Connect your realtor and your lender from day one. When I know your lender and your loan program, I can focus your search on homes that actually fit your approval, check condo documents before you view them, and tell you which offers will be competitive. It saves weeks, and it saves heartbreak.
A Word From Diana
That First "Yes" Is Worth the Paperwork
I have sat at kitchen tables with first-time buyers whose hands were shaking over a credit report, and I have watched those same buyers hand me the keys when they closed. Photo ID, two years of tax returns, three bank statements, none of it is fun, but every single page is a step toward a home that is yours. You are not the first person to feel nervous about this, and you will not be the last, but I promise you do not have to carry the worry alone.
One of my first-time buyer families wrote me the note I still keep: "We were terrified and wanted to make sure we chose someone who would truly listen. Diana was absolutely amazing. She has been incredibly knowledgeable, patient, and attentive throughout the entire process." That is the experience I want for you: informed, protected, cared for, and never rushed. Strangers become neighbors here fast, and I would love for that to start with a calm phone call about your numbers.
Whether you are a first-time buyer, a veteran using your VA benefit, or a family relocating from out of state, I will help you make sense of the process, protect what matters, and move forward with confidence. Let's make it fun, and let's make it yours.
Talk to you soon,
Diana Austin
Let's find out exactly what you qualify for
I work with trusted local lenders who will walk you through pre-approval with patience and straight answers. Call, email, or schedule a time to talk, and I've got your back from the first document to the final walkthrough.
Diana Austin • FIG Team • Fig Team EXP Realty LLC
Accredited Buyer's Representative • Waterfront Specialist • Military Relocation Specialist • Bilingual English & Spanish
FL License #3571079 • Equal Housing Opportunity